
Quick take — why this comparison matters
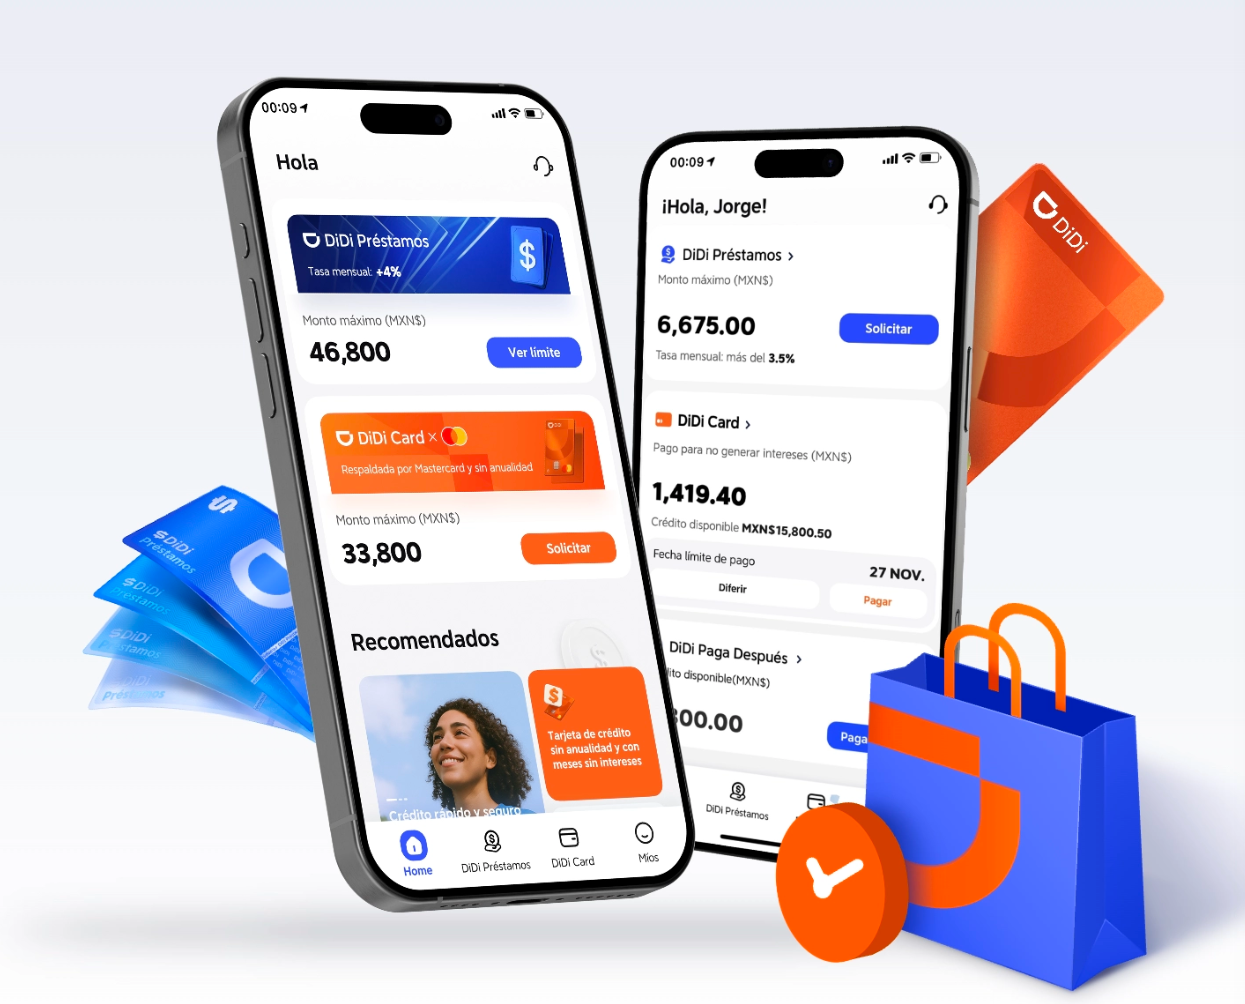
Mobile-first finance has moved from niche to mainstream, and that shift changes what drivers, gig workers and everyday customers expect from a benefits card. DiDi’s entrant into financial services aims to blend instant payouts and perks into a single app-led experience — see didi finanzas — and that’s exactly what puts it head-to-head with old-school card programs. This piece lines up user experience, fees, security and merchant reach so you can see where a digital wallet-first approach wins, and where traditional cards still hold ground.
User experience and onboarding
Onboarding with a mobile service is typically faster: app download, basic KYC, and you’re ready for peer-to-peer transfers or to request a payout. The didi finanzas app follows that pattern, prioritising a minimal flow and real-time balance updates. Traditional banks often require branch visits or longer verification windows, even for cards that promise similar benefits. From an API and integration perspective, fintechs favour lightweight APIs for instant payouts; legacy banks rely on more rigid infrastructure — which can slow new features down.
Costs, perks and card benefits
When it comes to fees and rewards, the trade-offs are clear. Mobile-first platforms tend to offer targeted cashback, fee-free balance transfers and driver-specific perks like instant settlements. Traditional card benefits, however, still shine in broad merchant acceptance and established loyalty programmes. Look at the maths: small percentage cashbacks and waived ATM fees add up for high-frequency users, while tiered bank rewards can eclipse that value for big spenders with travel or insurance bundles.
Security and compliance
Security protocols are non-negotiable. Two-factor authentication and end-to-end encryption are standard for reputable apps, while KYC and fraud detection keep both sides honest. DiDi-style offerings typically layer mobile security measures with fast incident responses, but established banks have deeper compliance frameworks and longer track records with regulators. For enterprise collaborations — like driver settlements or corporate benefits — that regulatory muscle matters.
Real-world performance: drivers, merchants and cities
Take Mexico City during the COVID-19 years: contactless payments and instant driver payouts weren’t just conveniences — they became essential. Gig workers leaned into instant-settlement options to smooth cash flow, and merchants adapted to mobile acceptance rapidly. That real-world shift shows why merchant acceptance and simple reconciliation tools are as important as flashy perks. If a card or app can’t be used widely at the corner store or fuel station, its value drops fast — even if it has great cashback.
Integration and ecosystem wins
APIs and partner integrations often decide long-term usefulness. Mobile platforms that expose clean APIs let fleet operators and third-party benefits providers plug in faster. Traditional banks offer broad network effects and established settlement rails, but fewer nimble integrations. For businesses automating driver payouts or bundling insurance and tax reporting, that ecosystem flexibility is the differentiator — worth prioritising if you need automation at scale. — Small detail, but it saves hours each month.
Alternatives worth weighing
If you’re comparing options, line up three buckets: incumbent banks with card rewards, challenger banks and fintech wallets, and specialised gig-focused finance platforms. Each has strengths: incumbents for reliability and acceptance; challengers for low fees and intuitive apps; specialised platforms for tailored payouts and driver benefits. Choose by use-case rather than brand gloss — whether that’s travel perks, instant payroll or everyday savings.
Three golden rules for choosing between mobile finance and traditional cards
1) Measure acceptance: prefer the solution that works at the merchants you actually use. 2) Prioritise cash flow features: instant settlements and low withdrawal fees matter if you’re paid frequently. 3) Check security + compliance: two-factor authentication, clear KYC and fraud protection are baseline requirements. Apply these metrics to shortlist, then test with a month-long pilot for real-world fit. In practice, that’s where DiDi Finanzas tends to show its value — a practical blend of payouts, perks and app-first design. –