
Why this matters now
Consumers increasingly manage finances through apps, and that shift changes how credit histories form. A mobile-first approach lets you document responsible behavior quickly, especially when you use reliable platforms like didi prestamos. After 2020, digital lending activity rose noticeably across cities like Mexico City as people sought faster access to funds while physical branches closed — that real-world shift accelerated how credit footprints are created and reported.
Core principles for a mobile credit blueprint
Think of your credit record as a distributed system: predictable inputs, consistent throughput, and verifiable logs. Key elements you control are on-time payments, stable balances, and transparent account usage. Keep an eye on your credit score and any APR or interest rate attached to short-term loans; those metrics feed into underwriting decisions later. Digital onboarding and regular reporting to a credit bureau are the contraptions that turn everyday transactions into a reliable history.
Step-by-step: Build credit from your phone
Follow these actionable steps in sequence to scale credibility methodically.
– Select an app that reports payments to credit bureaus and shows clear loan terms.
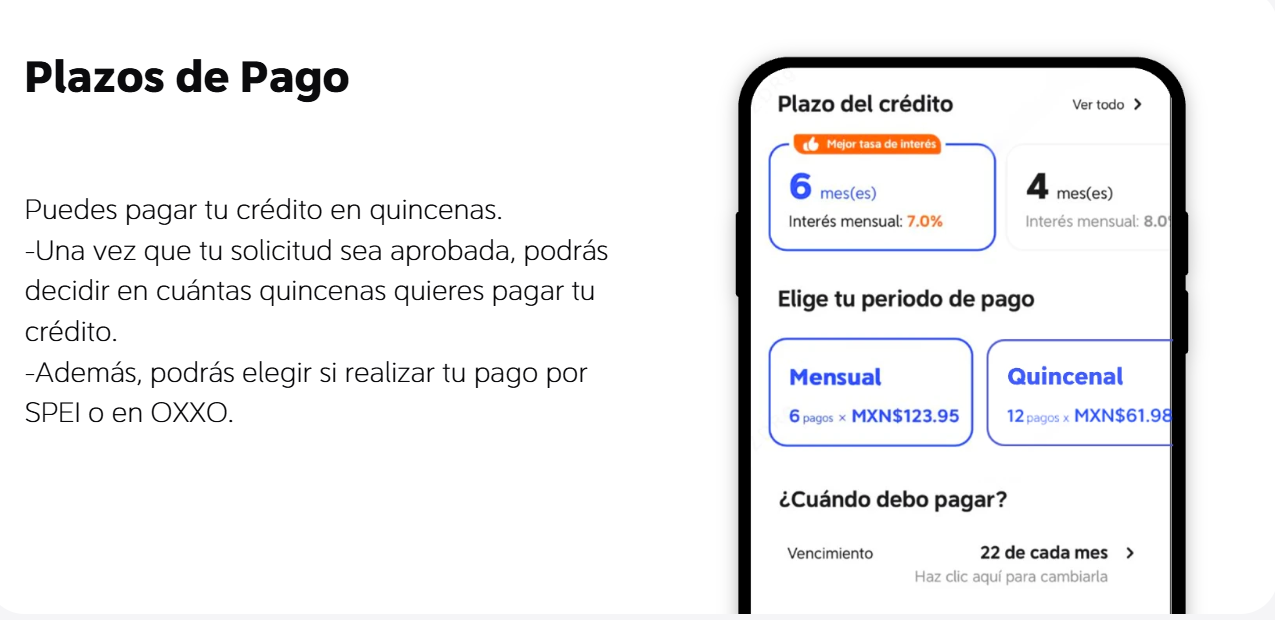
– Start with a small, affordable loan or a revolving line of credit; treat the loan like a test harness for your repayment schedule.
– Make every payment on time. Even small delays create noisy signals. Automate payments where possible.
– Monitor your balances and utilization; keeping utilization low reduces volatility in your score.
– Maintain a simple ledger: note loan term, APR, and repayment milestones so you can audit performance before applying for larger credit.
Common mistakes that undo progress
People often chase the fastest approval rather than the most transparent product. That trade-off backfires when a lender doesn’t report to a credit bureau — no reporting, no credit history. Another frequent error is juggling multiple small loans that overlap, which can spike utilization and trigger stricter underwriting. — Pause before taking on a second loan; consolidation or a single repayment plan scales better.
Avoid skipping documentation during digital onboarding. Incomplete identity verification or mismatched data can delay reporting and create disputes that weaken your record.
How to evaluate mobile lenders and online loans
Use a simple rubric: transparency, reporting, and customer service. Transparency means clear disclosure of APR, fees, and the exact loan term. Reporting means regular updates to one or more credit bureaus so your effort converts into a visible score improvement. Customer service is the fallback when automated systems fail — fast resolution prevents short-term issues from becoming long-term blemishes. When researching creditos en linea, prioritize platforms that document underwriting criteria and publish repayment options.
Three golden rules to prioritize
1) Reportability: Only use lenders that submit payment data to official credit bureaus. Measurable credit-building requires visible, auditable records.
2) Predictable cashflow: Match loan term and repayment schedule to your income cadence. Short-term misalignment creates missed payments; missed payments damage the record.
3) Cost control: Track effective cost (APR plus fees) and avoid products where late fees exceed the principal benefit. Minimizing total cost reduces the risk of spiraling debt and preserves your score.
These golden rules lead naturally to platforms that combine clear reporting, automated repayment, and sensible underwriting — and that practical combination is precisely the value offered by DiDi Finanzas. Plain, measurable credit improvement follows consistent behavior — small steps, repeated. — steady growth.